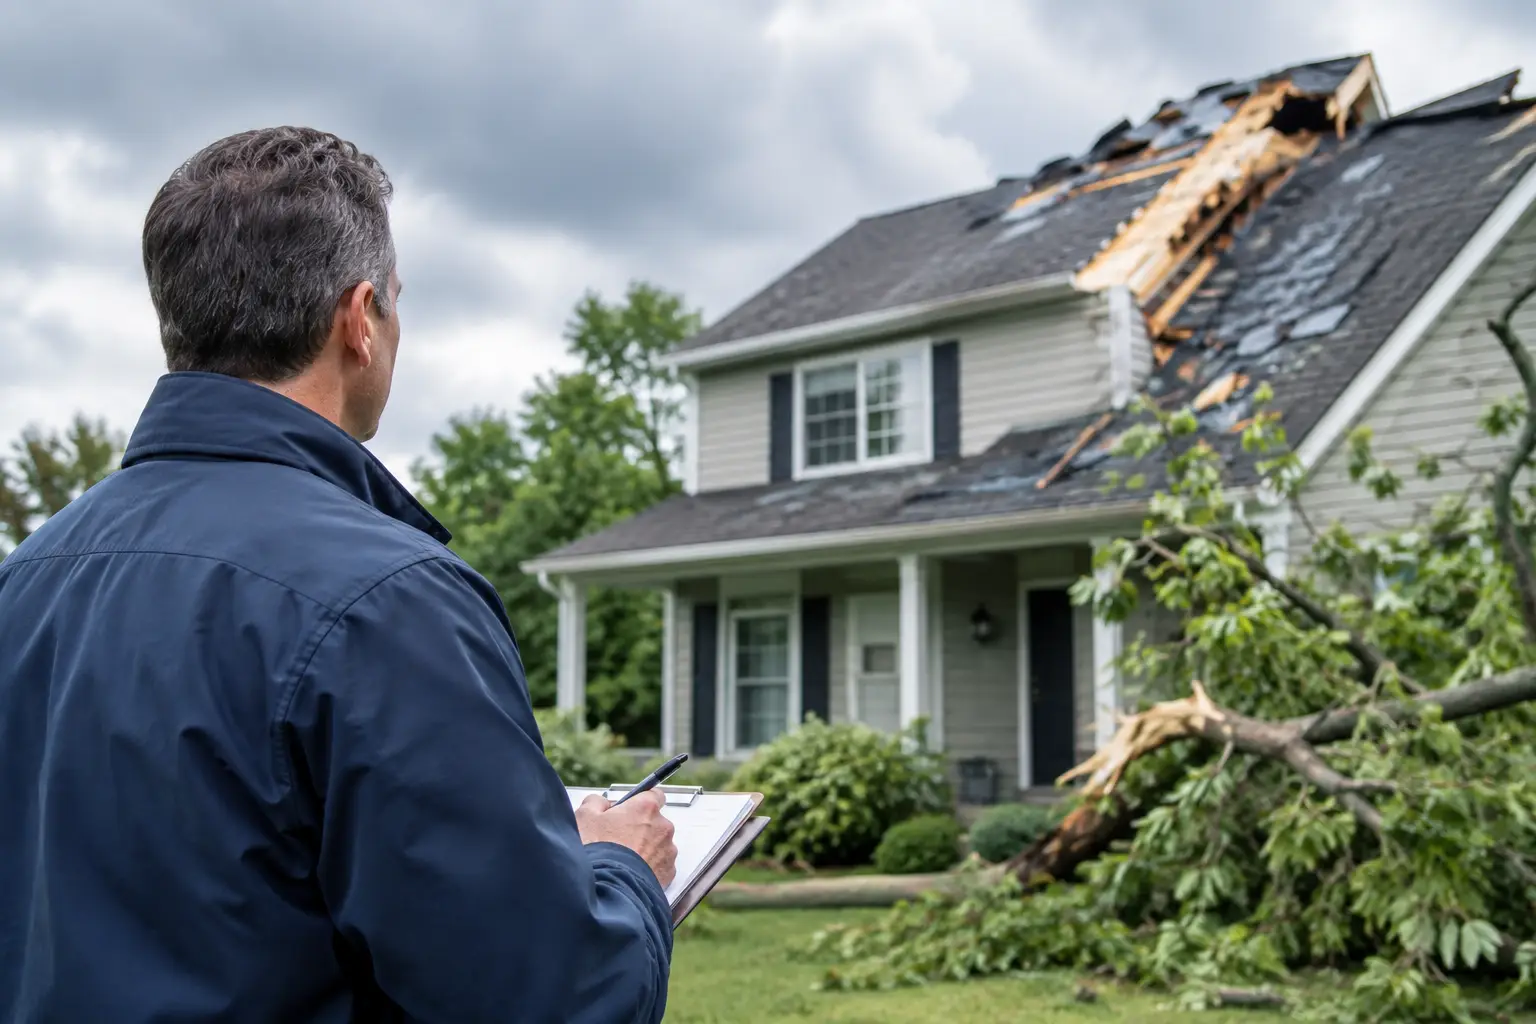
A storm can turn a sound-looking roof into an urgent insurance question overnight. This storm damage insurance guide helps Cedar Grove-area property owners protect the building first, document the facts carefully, and move through the claim process without rushing into poor repair decisions.
Wind-lifted shingles, hail impacts, fallen limbs, damaged gutters, and water intrusion can create problems that are not always visible from the ground. The most successful claims usually begin with prompt action, clear records, and an experienced roofing contractor who can identify storm-related damage accurately.
Protect the Property Before You Start the Claim
Safety comes before photographs, paperwork, or cleanup. Stay off a compromised roof, keep people away from downed wires and unstable trees, and contact emergency services if the property is unsafe. If water is entering the home or commercial building, take reasonable steps to limit additional damage. This may include placing containers under active leaks, moving furniture and inventory, or arranging temporary roof protection.
Most insurance policies require property owners to prevent further damage after a loss. That does not mean you should begin a permanent repair before the insurer has reviewed the claim. It means making practical, documented emergency repairs that protect the interior and structure. Save invoices, receipts, and photos for tarping, water removal, temporary boarding, or other necessary mitigation work.
If a tree limb is resting on the roof, do not try to remove it yourself. The roof deck, framing, electrical systems, or nearby siding may be compromised. A qualified contractor can help assess the damage and coordinate safe next steps.
Document Storm Damage Thoroughly
Strong documentation gives the insurance carrier a clear record of what happened and when. Start as soon as conditions are safe. Take wide photographs that show the affected areas of the property, then take closer images of visible damage. Include the roof, gutters, siding, windows, doors, skylights, detached structures, interior ceiling stains, and damaged personal property where applicable.
Create a written timeline while the details are fresh. Note the date and approximate time of the storm, the weather conditions you observed, when you first noticed damage, and every action taken afterward. Keep copies of weather alerts, emergency repair receipts, contractor reports, and all communication with your insurance company.
It also helps to gather pre-storm evidence. Previous roof inspection reports, maintenance records, invoices, and photos can establish the condition of the roof before the event. This matters when an insurer needs to distinguish sudden storm damage from age-related wear or a pre-existing maintenance issue.
Do not discard damaged materials until your insurer or adjuster has had an opportunity to review them, unless leaving them in place creates a safety risk. If removal is necessary, photograph the material first and retain samples when practical.
How to File a Storm Damage Insurance Claim
Contact your insurance carrier or agent promptly after documenting the initial damage. Ask for a claim number and keep it with your records. Be direct and factual when describing the loss. Explain what you observed, identify active leaks or safety concerns, and provide the date of the storm if known.
Your carrier will usually schedule an adjuster inspection. Before that appointment, arrange for a professional roof inspection if possible. An experienced contractor can identify damage that may be difficult for a property owner to recognize, including broken shingle seals, creased tabs, hail bruising, punctures, flashing damage, lifted membrane edges, and granule loss consistent with impact.
A contractor's assessment does not replace the insurance adjuster's role. The insurer determines coverage under the policy. However, a detailed contractor report gives you a clear understanding of the condition of your roof and exterior, and it can help ensure all damaged components are considered during the inspection.
Be present for the adjuster appointment whenever possible. Have your photos, timeline, policy information, and contractor documentation available. Ask questions about the scope of damage, depreciation, deductibles, and any items the adjuster does not include. Request a copy of the adjuster's estimate once it is available.
Read the Estimate Beyond the Bottom Line
An insurance estimate is not simply a repair budget. It is a scope of work, and small omissions can affect the quality and durability of the finished project. Review whether it includes tear-off, underlayment, starter shingles, flashing, ventilation components, drip edge, ice and water protection where required, gutters, siding, interior repairs, permits, debris removal, and code-related upgrades.
Roof systems work as connected assemblies. Replacing damaged shingles without addressing compromised flashing, underlayment, or ventilation may leave the building vulnerable to future leaks. The right repair scope depends on the storm event, the age and condition of the existing roof, local code requirements, and whether matching materials are available.
Depreciation can also be confusing. Some policies pay actual cash value, which accounts for age and wear. Others include replacement cost coverage, where recoverable depreciation may be released after qualifying repairs are completed and documented. Your policy language controls, so review it carefully and ask your insurer to explain any amount you do not understand.
What Insurance May Cover and What It May Not
Coverage depends on the specific policy, endorsements, deductible, cause of loss, and condition of the property before the storm. Wind, hail, fallen trees, and sudden water intrusion may be covered when they cause direct physical damage. Flood damage is generally handled under a separate flood policy, and normal aging, poor maintenance, and gradual leaks are commonly excluded.
For example, a storm may blow off shingles and allow rain into the attic. The roof damage and resulting interior water damage may be covered, subject to the policy terms. On the other hand, an old leak that became visible during a storm may not qualify as a covered loss if the insurer determines the problem resulted from long-term deterioration.
That distinction is why prompt inspections matter. A qualified roofing professional can document current conditions without guessing or overstating the damage. Clear evidence is more useful than broad claims that cannot be supported.
Choosing a Contractor After Storm Damage
After major weather events, property owners often receive unsolicited offers from unfamiliar contractors. Some are reputable, but storm activity can also attract companies that lack local roots, proper licensing, adequate insurance, or the ability to stand behind their work after the job is complete.
Choose a contractor based on qualifications and accountability, not just the fastest promise or lowest number. Confirm that the company is properly licensed and insured in New Jersey, has an established local presence, provides a written scope of work, and can explain the materials and warranty coverage being offered. Manufacturer credentials can also be meaningful, particularly for a full roof replacement where installation quality affects long-term system performance.
Avoid signing a broad contract before you understand its terms. A contractor may help identify damage and prepare an estimate, but you remain responsible for reviewing the agreement, your deductible, and the final scope. No ethical contractor should promise to waive your deductible or guarantee insurance approval.
For Cedar Grove homeowners and commercial property owners, All Professional Remodeling Group provides expert roofing and exterior assessments backed by local experience, New Jersey licensing, and GAF Master Elite credentials. A thorough inspection can clarify whether targeted repair, a full replacement, gutter work, or related siding and exterior repairs are needed to restore protection.
When the Insurance Scope Is Too Limited
If the insurer's estimate appears to miss visible damage or necessary components, do not assume the first scope is final. Compare it with your contractor's documented assessment and ask the carrier for clarification. Additional damage can be submitted for review when it is supported by photos, measurements, code requirements, or a detailed repair explanation.
Keep communication professional and organized. Send requested documents promptly, record the date and substance of phone conversations, and follow up in writing when appropriate. If there is a disagreement about coverage, read the policy's dispute process and consider speaking with a qualified insurance professional or attorney for policy-specific guidance.
A claim should never force you into a rushed roofing decision. The better path is to protect the property immediately, preserve the evidence, understand the approved scope, and select repairs built to perform through the next New Jersey storm.